AXA
Note: This is a daily stock update and the information stands true as of 15/09/26, 09:00 CET
Company Update:
AXA has unveiled its strategic plan and targets for the 2027-2029 period, including:- Underlying EPS CAGR of between 7% and 9% for 2026E-2029E, a slight upgrade from the previous strategic plan's target of 6% to 8%.
- Underlying return on equity of between 15% and 17% over 2027E-2029E.
- A mid-teens CAGR in book value per share, inclusive of cumulative dividends, over 2026-2029E.
- Approximately €25bn in cumulative organic cash upstream over 2027E-2029E.
AXA also reiterates its total payout ratio target of 75% of underlying EPS, comprising a 60% dividend payout ratio and a 15% annual share buyback payout ratio.
For FY26, AXA reaffirms that underlying EPS growth will be at the top end of its 6-8% target range, and that underlying ROE will be at the top end of its 14% to 16% target range.
Our view: The key figure is the underlying EPS growth target of 7-9% per annum. While this is unlikely to come as a major surprise to the market, we still believe it could trigger a gradual rerating of the stock: AXA has underperformed Generali and Allianz in recent months, largely due to its greater exposure to P&C commercial insurance, a segment that is currently softening. AXA explicitly stresses that its targets take this softening into account.
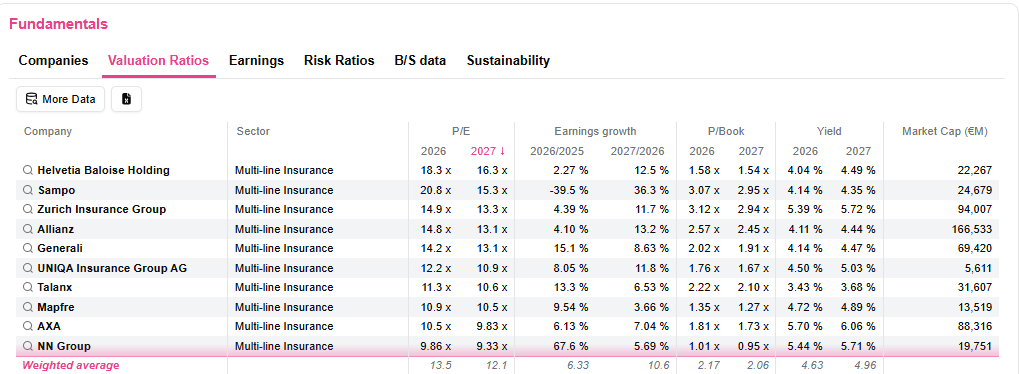
AXA shares currently trade at a c. 20% discount to the sector, on a P/E of 10.5x, and offer a 7.4% total shareholder return yield. We therefore see significant upside to the share price if AXA delivers on its targets. The key question is whether management will convince investors and analysts… More details to follow after today's analyst presentation, scheduled for 10:30 this morning.
Expert Opinion:
We must confess we are less bullish than our analyst on that new strategic plan. We don't find the announcement as a game changer. AXA is a very solid company and trades on what are objectively attractive valuation ratios (PE26 of 10.5x with a 5.7% dividend yield). Yet we are not sure this will trigger any significant rise of EPS by the consensus. Furthermore, the economic situation is more likely to worsen than improve over the next few months and sinistrality tends to increase with economic downturns. We see no reason to rush into the sector at this stage and would rather wait on the sideline. But if you want to be exposed to insurance, Axa is probably the stock offering the best risk/reward profile at this stage.
For daily updates, subscribe to our newsletter and for detailed information, reach out to us at sales@alphavalue.eu
We must confess we are less bullish than our analyst on that new strategic plan. We don't find the announcement as a game changer. AXA is a very solid company and trades on what are objectively attractive valuation ratios (PE26 of 10.5x with a 5.7% dividend yield). Yet we are not sure this will trigger any significant rise of EPS by the consensus. Furthermore, the economic situation is more likely to worsen than improve over the next few months and sinistrality tends to increase with economic downturns. We see no reason to rush into the sector at this stage and would rather wait on the sideline. But if you want to be exposed to insurance, Axa is probably the stock offering the best risk/reward profile at this stage.
For daily updates, subscribe to our newsletter and for detailed information, reach out to us at sales@alphavalue.eu
Subscribe to our blog
Alphavalue Morning Market Tip
Another late-stage clinical trial setback for AstraZeneca.
Alphavalue Morning Market Tip
Average H1 26 results, Belron strategic review (IPO) and new CEO.
Alphavalue Morning Market Tip
Strong Q2 (May-July) and encouraging trading statement for August.