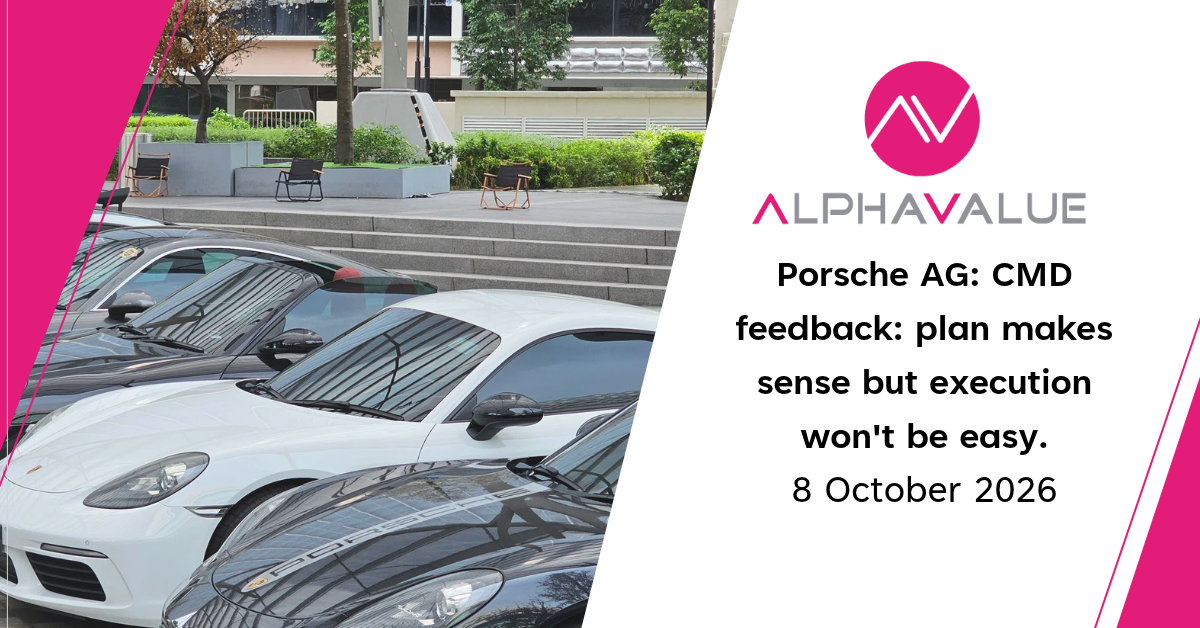
Porsche AG
Note: This is a daily stock update and the information stands true as of 08/10/26, 09:00 CET
Company Update:
Porsche held its CMD and disclosed its new financial targets and revised its strategy, focusing on value over volume.Targets: medium-term Group RoS of 10-15%. The timing was not specified but is implied for around 2030-31.
-
Value over volume: volumes are being significantly reduced, to around 220k units in 2027.
-
Muted profitability near term: with new models only arriving in 2028, mix and pricing will not offset lower volumes until the end of 2028.
-
Brand strength intact: the Mission S, a new model positioned above the 911 that will be presented globally, was received with real excitement, particularly when the engine was heard.
-
Shareholder returns: strong emphasis on a payout ratio of at least 50%, with clear potential to go above.
-
Management: the CEO was very present throughout and well received by investors.
-
Conservative assumptions on markets and macro, particularly China, where Porsche targets about 10% of total shipments in the medium term and 15% in the long term.
-
911 pricing:around 5,000 units at an ASP of about €270k, with a target above €330k (+20%).
-
Ferrari-style approach: exclusivity, scarcity, and personalization to drive mix and pricing. Solid strategy but will never be able to reach the levels of Ferrari.
Overall: the strategy is strong: higher-margin and more expensive vehicles, cost reduction, and lower volumes to protect exclusivity. However, the financial benefits will only come through from 2029. We do not expect a significant stock price recovery until 2027-2028.
Expert Opinion:
The strategy makes sense, and the previous ambitions of making Porsche a mass luxury carmaker were over-optimistic. Re-anchoring Porsche to its more traditional footprint makes sense, but the execution will take time. We see no fundamental reason to be long Porsche just now. Interestingly, yesterday we had news (or more precisely, rumors) that the French and German governments could agree to try to reverse the 2035 ban on ICE cars at the EU level. This would be a potential game changer for the European car industry and would be positive for all manufacturers. We believe Volkswagen, in this scenario, would be the one that could bounce most. Indeed, the recent shift in perception that they can restructure and cut costs is a game changer if ICE comes back into the picture over the long run. Please note that in the short term, EV cars will keep selling because gas prices are simply too high. And Chinese and TEsla's cars are simply better than European ones at this stage.
The strategy makes sense, and the previous ambitions of making Porsche a mass luxury carmaker were over-optimistic. Re-anchoring Porsche to its more traditional footprint makes sense, but the execution will take time. We see no fundamental reason to be long Porsche just now. Interestingly, yesterday we had news (or more precisely, rumors) that the French and German governments could agree to try to reverse the 2035 ban on ICE cars at the EU level. This would be a potential game changer for the European car industry and would be positive for all manufacturers. We believe Volkswagen, in this scenario, would be the one that could bounce most. Indeed, the recent shift in perception that they can restructure and cut costs is a game changer if ICE comes back into the picture over the long run. Please note that in the short term, EV cars will keep selling because gas prices are simply too high. And Chinese and TEsla's cars are simply better than European ones at this stage.
Please also note that OP Mobility issued a profit warning as 'market conditions' (read: OEM demand) deteriorate faster than expected. This is a negative X-read for Valeo and Forvia in our coverage. This could only be the beginning.
For daily updates, subscribe to our newsletter and for detailed information, reach out to us at sales@alphavalue.eu
Subscribe to our blog
Alphavalue Morning Market Tip
Acquisition of PTC for USD23.7bn will stretch the balance sheet to the extrem.