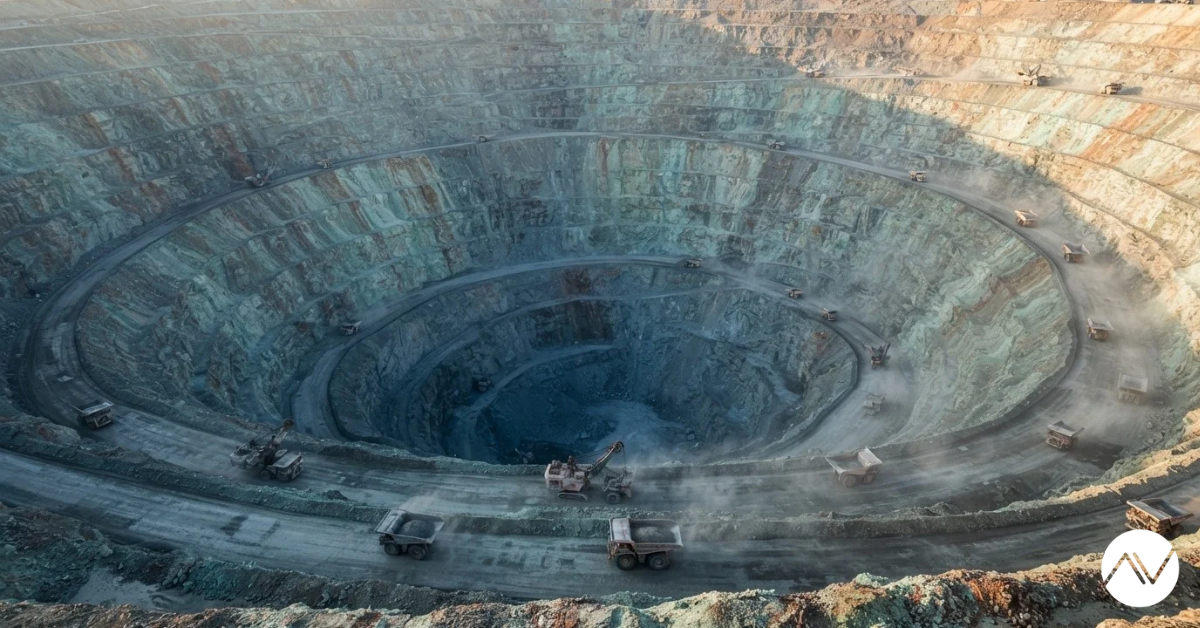
Anglo(-Teck)’s Copper Fable Nearing An End?

Fourteen months after Anglo American (REDUCE; UK), the UK diversified, though copper-heavy, mining giant, talked Teck Resources (not covered; Canada) into a “merger of equals”, the deal is nearly done. One signature is still outstanding, and it’s Beijing’s.
Meanwhile, Dr. Copper has been doing most of the work – LME copper hit a record $14,822/t last month, and Anglo-Teck, valued at $53bn at announcement, was worth just under $90bn combined by mid-October. That’s an impressive return on a marriage that has yet to be consummated. That said, this strong return is as much a sector story as an Anglo one.

A mixed journey, now somewhat less mixed
Mirrored the sector’s return frenzy
A mixed journey, now somewhat less mixed
H1 26 EBITDA rose 35% yoy to $4.0bn, a touch ahead of consensus, on stronger copper earnings, iron ore support and cost savings. Net loss was $858m (but lower vs. $1.9bn), mostly on a met coal write-down – the restructuring still costs money even as the assets leave. The interim dividend tripled to $0.23/share, though below $0.27 pencilled in by markets.
Disposals are moving, though not all at the same pace
Met coal: after Peabody walked away, the Australian assets were re-sold in May to Dhilmar for up to $3.875bn, taking total coal proceeds to c.$5bn. Second time lucky, as they say.
De Beers: carrying value cut to $2.3bn (from >$4bn). A consortium, now Botswana’s preferred bidder (with Richemont (REDUCE; Switzerland) in talks to join), is the frontrunner, though Botswana, which plans to double its stake to 30%, holds a right of first refusal. With coal proceeds due, the balance sheet hardly needs a fire sale, though a reported c.$1bn offer looks rather like one. Diamonds may be forever, but Anglo’s patience with them, evidently, is not.
Brazilian nickel: remains the weak spot. The European Commission is reportedly leaning towards blocking the $500m sale to China’s MMG (decision due 21 December), despite MMG raising its European ferronickel supply offer to 16kt/yr. Failure likely means care and maintenance, mining’s polite term for closure.
Heavyweight is still at the weigh-in
The mega-merger approval list looks comforting: shareholders, Ottawa, the EU, US, Japan, Chile and South Korea have all signed off. China’s SAMR is the holdout, seeking guaranteed concentrate supply to Chinese smelters (no asset sales, at least for now). Interestingly, with China facing its worst feedstock shortage in decades, Beijing seems less interested in the bride than in the dowry. Remember, it held out on Glencore (ADD; Switzerland)-Xstrata merger too, blessing the deal only once Glencore sold Peru’s Las Bambas (which MMG duly bought). Perhaps then, an accommodating EU on MMG’s nickel purchase could smooth things in Beijing, though Brussels seems minded to do the opposite.
Anglo-Teck deal closing is still targeted by March 2027.
The industrial logic stands, with c.$800m p.a. of pre-tax synergies before any Collahuasi–QB upside. That said, Teck’s QB remains a work in progress, with weather cutting Q3 output to 47.2kt (from 55.8kt), and Teck’s CAD1.6bn Q3 profit shows how much a record copper price can cover up. Moreover, Silicon Valley has discovered that the cloud runs on copper, with tech groups eyeing Anglo equity or offtake.
At sector level, BHP’s late-2025 return lasted 24 hours, and Rio Tinto (ADD; UK)-Glencore talks collapsed in February over valuation/control. Copper M&A, it seems, is a sport with plenty of talks but few deals, which makes all-stock offers without big premia look more sensible.
Dr. Copper too can fall sick
Interestingly, the louder the copper bulls get, the more company the sceptics seem to have. In October, the International Copper Study Group raised its 2026 refined surplus forecast to 104kt and sees it more than tripling to 368kt in 2027, as new smelting capacity and more scrap (high prices being the best recycling incentive) outpace demand growth of just 1.5% this year. China (c.60% of global refined consumption) is not much help either: CRU puts its demand flat yoy, with a c.5% fall in domestic use offset only by higher exports.
Moreover, part of the rally looks borrowed rather than earned. US inventory building ahead of a refined copper tariff decision (pencilled in at 15% from January 2027) has tightened supply elsewhere, and clarity, perhaps coloured by Trump’s midterm drubbing, could finally help rationalise prices. Equally, should the Nvidia governance debacle dent the AI capex story, data-centre demand (copper’s newest bull case) could lose some of its shine. Remember, none of this undoes the medium-term mine supply story: Grasberg and Kamoa-Kakula remain constrained, and Chile is declining. But with copper at record levels, the gap between price and fundamentals is harder to ignore, and miners priced for perfection could be the first to find out – more so when facing output and possible cost challenges. That should worry the likes of Anglo, for whom copper is c.60% of gross assets and c.70% of H1 EBITDA.
Mispriced for perfection
Market’s dash for Anglo’s shares seems to have priced in a perfect merger with Teck. That’s seldom the case for mega-M&A, more so when the bulk of the value creation lies in LatAm, where operating risks abound (labour, weather, water, politics). Our c.12% downside reflects those concerns. Anglo trades on 20x 2026 PE (vs. a 13x average since 2015) against 15x for better-quality AV peers – a sign of investors overlooking quality and chasing anything copper-heavy. Once the deal-closing celebrations are over, the market could get its reality check, and better-priced names like Glencore and Rio Tinto could be (final!) winners on risk-adjusted returns.

Subscribe to our blog
European defence stocks have stalled at luxury-goods valuations while national rivalries, Germany&...
Microsoft is paying a third of its workforce to leave - and if Europe follows, the earnings boost comes...