ASM International
Note: This is a daily stock update and the information stands true as of 28/10/26, 09:00 CET
Company Update:
Revenue came at €1,159m (consensus €1,100m) driven by leading-edge logic and memory.
Sales increased 44% YoY at constant currencies, with advanced logic/foundry the largest growth driver. Strong 2nm investment, the first solid contribution from 1.4nm, and higher HBM-related DRAM demand supported growth. Mature logic/foundry, particularly China, also remained robust.
Adjusted operating profit of €387m (c6% better than expected), operating margin reached 33.4%
Q4 guidance slightly ahead: Revenue guidance of €1,230m ±5% vs €1,209m consensus.
2027 guidance is the standout: ASMI now expects revenue above €5.7bn (vs EUR5.3-5.4bn for consensus), achieving its original 2030 target three years early.
Shareholder returns: New €300m share buyback program announced.
Expert Opinion:
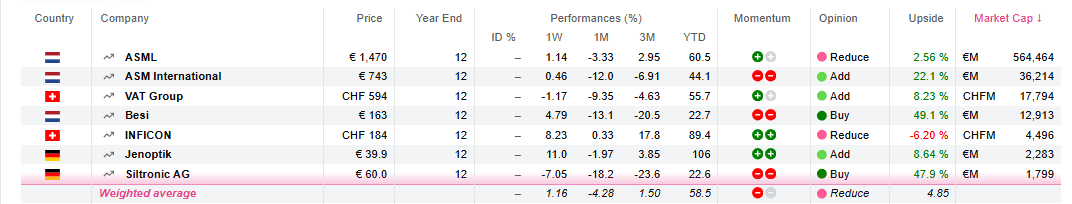
Very strong results and raised 2027 guidance is good news. We know demand for semiconductors is very strong right now, and that's already reflected in the sector's valuation. With SK Hynix also a blowout this morning, we expect the sector to do well. Following the drop in the sector, we now have a few positive ratings on the sector. But we personally wouldn't chase the move upwards; we still feel the valuation is high, and AI capex financing remains a conundrum. Too risky to our liking.
For daily updates, subscribe to our newsletter and for detailed information, reach out to us at sales@alphavalue.eu
Very strong results and raised 2027 guidance is good news. We know demand for semiconductors is very strong right now, and that's already reflected in the sector's valuation. With SK Hynix also a blowout this morning, we expect the sector to do well. Following the drop in the sector, we now have a few positive ratings on the sector. But we personally wouldn't chase the move upwards; we still feel the valuation is high, and AI capex financing remains a conundrum. Too risky to our liking.
For daily updates, subscribe to our newsletter and for detailed information, reach out to us at sales@alphavalue.eu
Subscribe to our blog