Ferrari-Exor-Hermes
The first is against its parent company, Exor.
The second is against THE other scarcity play, Hermès
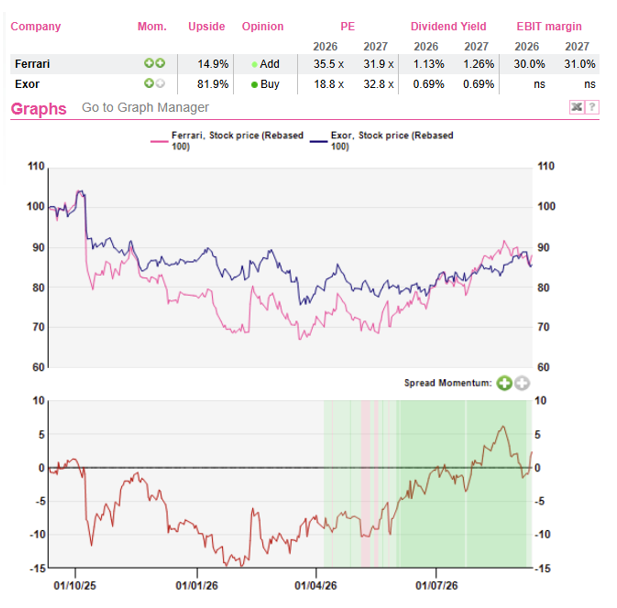
Start with the Long Ferrari Short Exor.
Exor owns 19.5% of Ferrari. Ferrari accounts for 38% of Exor GAV. Fundamentals (table below) call for exiting Ferrari and buying into Exor with an 82% upside potential. Looking at the strict valuation gaps, the Long Ferrari Short Exor would generate a 37% loss as per AlphaValue computation of long short outcomes… Still investors are not impressed by Exor’s stakes in Stellantis, CNH or Lingotto and would seemingly rather stick to the direct exposure to sports wheels as highlighted by the green shaded area below which tracks the momentum of the trade.
Exor is cheaper. That is not enough.
Now move on to the Long Ferrari Short Hermès.
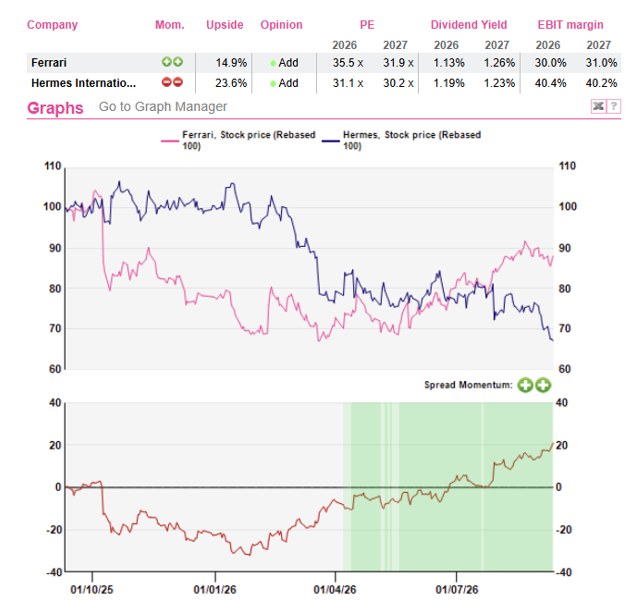
For context, AlphaValue bit the bullet on 14-09 and slashed its target price on mighty Hermès by c.20%. There is still another 23% upside potential left to this €150bn market cap. The stock is back to its 2023 levels and trades around 30x, some sort of a floor observed over AlphaValue’s 20y coverage history. One would expect some renewed investor interest.
The comparison with Ferrari shows that confidence in luxury cars is way stronger than in luxury bags, although both are scarcity management efforts. A long Ferrari Short Hermès would yield a 7% theoretical loss (on AlphaValue’s computation of long short outcomes) but here again, investors are not interested in reversing the trade as attested by the green shaded area that measure the strength of momentum behind the trade.
The conclusion is that it is hard to topple Ferrari. This was certainly not the dominating sentiment when the Luce was revealed a few months back. Well done. Modena thus beats Turin and Paris.
Subscribe to our blog
Over ten years, UK corporates beat their French peers on 7 of 13 paired comparisons in euros - and ...
European defence stocks are lagging the market as budget constraints and fast-shifting threats clou...